☕ DrinkCoffeeAndProfit
Smart money moves before breakfast
Inspiration Quote for the Day
“The large print giveth and the small print taketh away.”
Tom Waits
The Morning Ritual
Twelve Months at Zero, Then a Bill for the Whole Thing
You have seen the sign at the furniture counter, the appliance aisle and the dentist’s front desk. No interest if paid in `12` months. It reads like a `0%` card. It is a different product. The ending is different too.
The difference only shows up on one day, and by then the money is already gone.
· · · Partner Message · · ·
Green Coffee Company
The Next Starbucks Is Brewing in Colombia
In 1992, Starbucks went public at a split-adjusted price of approximately $0.27.
Today, the stock trades around $96.
That is a gain of roughly 35,000%.
Put another way…
That turns $100 into roughly $35,000…
$500 into roughly $177,000…
And a tiny stake of $1,000 into roughly $355,000.
But unless you invested in Starbucks back in 1992, that opportunity is already gone.
The bigger question is: Where could coffee’s next major growth story come from?
The global coffee market is projected to reach approximately $380 billion by 2033. And its next breakout company may not be built around thousands of cafés.
It may begin with the farms…
And that’s the opportunity that could dwarf Starbucks returns.
Meet Green Coffee Company.
It owns approximately 45 Colombian farms and 10 million coffee trees.
It also holds exclusive third-party rights to distribute Juan Valdez coffee across U.S. and Canadian retail and institutional channels.
Those products are already reaching Target, Walgreens and thousands of North American retail locations.
And individual investors can now own a stake while the company is still private. No accreditation required.
Our share price is changing after September 30th.
Under Regulation A, a company may change its share price by up to 20% without requalifying the offering with the Securities and Exchange Commission.
Private investments are speculative and illiquid. Returns are not guaranteed. Review the offering circular before investing.
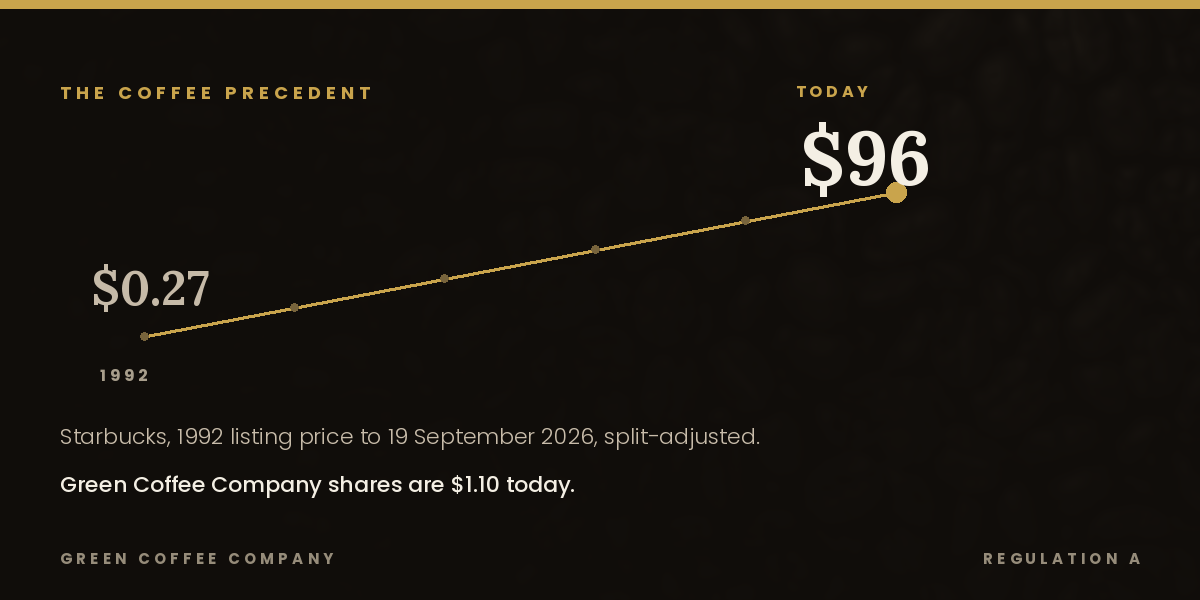
In One Sip
► Deferred interest is not a `0%` rate. It is interest that is recorded and held back, then charged if any balance is left at the end. Source: Consumer Financial Protection Bureau.
► When it triggers, the charge is calculated on the original purchase amount from the purchase date, not on what is left. Source: CFPB.
► About one in five deferred interest promotional balances ended with that retroactive charge applied. Source: CFPB research.
► `94%` of deferred interest cards come from three banks: Synchrony, Citi and Comenity. Source: WalletHub study of `72` large retailers.
► The quiet part: on a real `0%` intro card, when the promotion ends you owe interest on what remains. On a deferred plan you owe it on everything you bought. Source: CFPB.
Why It Matters for Your Money
Put a sofa on it. `$3,000`, twelve months, nothing due in interest if it clears in time. You pay all year. You finish with `$200` still sitting there.
On a real `0%` card that `$200` starts earning interest and nothing else changes. On a deferred plan the clock runs backwards. The rate applies to the full `$3,000` from the day you signed.
At a store rate near `30%` that is roughly `$900`. The last `$200` of a sofa cost four times itself.
There is a second trap under the first. Say the card also carries ordinary purchases. Anything above the minimum usually goes to the highest rate balance. The promotion you are racing gets nothing extra. You can ask the issuer to redirect it, and most people never do.
· · · Partner Message · · ·
0% intro APR credit cards
A simple credit card switch could help you get out of debt faster. With a 0% intro APR on balance transfers and purchases, you can put more money toward paying down your balance, without throwing it away on interest. See some of the top picks now.
This is an advertisement.
The Wealth Angle
Two things can be true. Deferred interest is legal, disclosed and sometimes the cheapest money in the room, because most people do clear it in time. It is also built so that the one day you slip is the day it collects a year of interest at once.
The regulator has written to these issuers and asked them to use plain `0%` promotions instead. One large retailer dropped the practice on its own card. The rest kept it, which tells you what the feature is worth to them.
My rule here is one question at the counter, asked out loud. Is this deferred interest or a true `0%` rate. If the answer takes longer than a sentence, the answer is deferred.
Then I divide the purchase by one month fewer than the promotion. Twelve months becomes eleven payments. The spare month catches whatever the arithmetic missed.
☕ Key Insight:
A `0%` promotion forgives the interest. A deferred promotion only postpones it. The sign in the window is the same size for both. Only one of them holds when you finish a month short.
Coffee Break Move
If you are comfortable: Pull any store or medical card you opened this year and find the promotion end date on the statement. Write it on the calendar a month early. That single line is the whole defence, and it takes about a minute per account.
If you are stretched: Call the issuer and ask two things. What is the exact payoff figure on the promotional balance. Can payments above the minimum go to it instead of the rest of the card. Both requests are ordinary. Both are free.
The sign says no interest for twelve months. The contract says interest is being counted the whole time. Only one of those two is written down in a place that matters.

Keep Reading