☕ DrinkCoffeeAndProfit
Smart money moves before breakfast
Inspiration Quote for the Day
“The question isn’t at what age I want to retire, it’s at what income.”
George Foreman
The Morning Ritual
Uncle Ernie Is Maxing His HSA at 64. His Medicare Card Could Undo Six Months of It.
My uncle Ernie is 64 and still drives a forklift three days a week. He keeps his benefits folder in a red accordion file on top of the fridge. This fall he plans to max out his health savings account, every dollar the law allows, before he retires at 66.
The plan is smart for two more years. Then one routine form reaches back. The one that starts his Social Security can turn months of good saving into a tax problem.
An HSA shields money from taxes. Our partner below is worried about a different threat to savings: the dollar itself.
· · · Partner Message · · ·
They Crashed the Dollar in 1985. Again Now?
In 1985, the world’s most powerful players struck a deal and drove the dollar down on purpose, and everyday savers paid the price. Insiders say a new version, the “Mar-a-Lago Accord,” is forming now. Same playbook, your dollars on the chopping block. See the 3 strategies smart Americans use to protect their wealth before the door slams shut.
Get Your Free Info Kit Now
This is an advertisement.
In One Sip
► For 2027, the HSA limit rises to `$4,500` for self-only coverage and `$9,000` for family coverage. Source: IRS Rev. Proc. 2026-24.
► Savers 55 and older can add `$1,000` more. That catch-up is fixed by law and has never risen with inflation. Source: IRS.
► Money put in through payroll skips federal income tax and the `7.65%` Social Security and Medicare tax. Source: IRS Publication 969.
► Once you are enrolled in any part of Medicare, you can no longer contribute to an HSA. Source: IRS Publication 969.
► The buried part: sign up for Medicare Part A after 65, and coverage is backdated up to six months. It never reaches back before your 65th birthday. Contributions made in those months become excess. Source: Social Security Administration.
Why It Matters for Your Money
Ernie has family coverage and is over 55, so his 2027 ceiling is `$10,000`.
Through payroll, in the `22%` bracket, that saves him about +`$2,965` in federal and payroll taxes. That part is a great deal.
Now the trap. When he applies for Social Security at 66, Medicare Part A starts automatically, and it reaches back six months.
If he keeps contributing right up to that day, about `$5,000` lands in months he was already covered. That money becomes excess, and the IRS charges `6%` a year on it, about `$300`, until it comes out.
Sound familiar? The fix costs nothing. Stop contributing six months before you apply.
Ernie’s plan is about money he can leave alone for years. Our partner below draws a sharp line between assets you hold and assets you use up.
· · · Partner Message · · ·
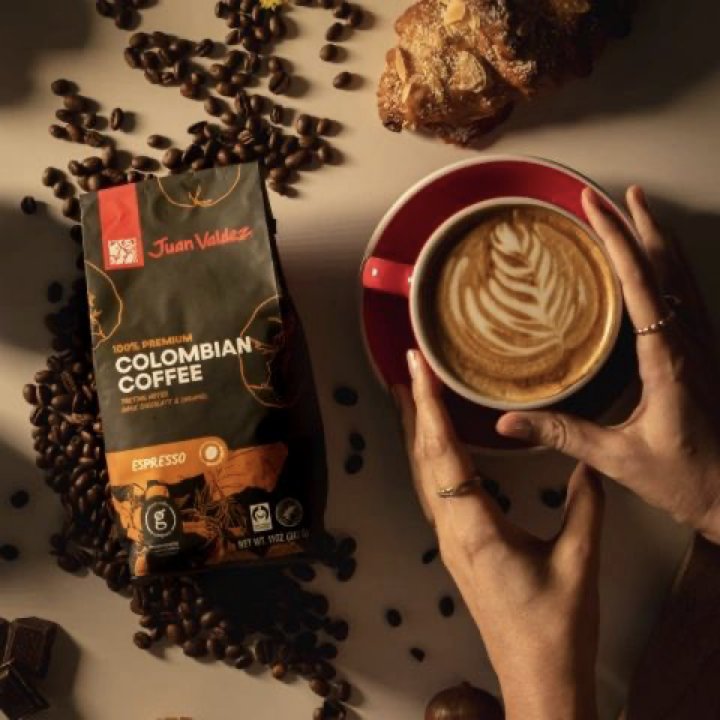
Juan Valdez Colombian coffee
Thirty-five years pricing physical assets taught me one distinction I now use on everything. Stock demand or flow demand.
Gold is stock. Nearly every ounce ever pulled out of the ground still exists, sitting in a vault or a drawer or around somebody’s neck. Demand for it is a decision to hold.
Coffee is flow. It is grown, shipped, roasted, brewed and gone. Seventy-three percent of Americans drink it daily. That demand does not have to be persuaded. It has to be supplied, again, tomorrow morning.
I looked at a private producer this week on that basis.
Green Coffee Company farms 45 properties in Colombia, more than 10,000 acres. Projected harvest this year: 5.1 million pounds of unroasted coffee. Last year: 2.3 million. Milling capacity above a million pounds a week, the largest in the country.
The flow already has somewhere to go. 3,000+ stores. 130+ grocery chains. 21 states. Walgreens live in 1,700 locations. Private label into Carnival Cruise Line, the U.S. National Parks and the UFC. You have very likely drunk the product already without knowing whose farm it came off.
Revenue: $1 million in 2021. $26 million in 2025.
My read. A metal position pays you nothing and asks nothing; you hold it and wait for the regime to change. A flow asset pays you only if the operator keeps executing, every harvest, every shelf reset, every quarter. Different risk entirely. Do not confuse the two because both come out of the ground.
Terms: $1.15 a share, $1,000.50 minimum, no accreditation, up to 20% bonus shares at higher tiers. Unlisted, illiquid, transfers restricted, total loss possible. Size it like growth equity, because that is what it is.
The metal waits for you. The harvest does not.
Review the offering
Rights apply to retail and institutional sales in the U.S. and Canada (non-cafe business) and are governed by a 10-year agreement to manufacture and distribute the iconic Juan Valdez® brand in the U.S. and Canada. Juan Valdez®, Procafecol S.A., the National Coffee Federation of Colombia, and any of their respective affiliates (collectively, the “Juan Valdez Parties”) are not sponsors, issuers, co-issuers, promoters, guarantors, underwriters, placement agents, or participants in any manner in this investment offering. The Juan Valdez Parties have not reviewed, approved, authorized, endorsed, recommended, or verified this offering, any related offering materials, or any statements made herein, and do not express any view or opinion regarding the merits, risks, or suitability of this investment. Any reference to the “Juan Valdez®” brand or related trademarks is made solely for the limited purpose of describing an existing commercial agreement relating to the manufacture, marketing, and sale of certain coffee products. Such agreement does not extend to, and expressly excludes, any securities offering, fundraising activity, investment program, or capital-raising transaction. Investors should not rely on the existence of any trademark license, brand association, or commercial agreement with the Juan Valdez Parties as an indicator of financial performance, investment quality, creditworthiness, risk mitigation, or likelihood of success of the issuer or this offering. The continuation of any commercial agreement is subject to contractual terms and conditions and may be modified or terminated, and no assurance is given that any such relationship will continue for any period of time. No Juan Valdez Party assumes any responsibility or liability for the accuracy, completeness, or adequacy of the information contained in this offering, nor for any investment decision made by any investor.
This is an advertisement.
The Wealth Angle
Here is where it gets interesting. An HSA is the only account that can be tax-free going in, while growing, and coming out for medical bills.
After 65, you can also pull money for anything else. It is taxed like an IRA withdrawal, with no penalty. Medical costs in retirement are the one expense almost every household will have.
Think about that for a second. Many people treat the HSA like a checking account for copays, then spend it down every year.
I think the smarter move is to pay small bills from cash if you can. Keep the receipts and let the HSA grow. You can reimburse yourself years later.
One more wrinkle for couples. If both spouses are 55 or older, each catch-up has to go into that spouse’s own HSA. One account cannot hold both.
· · · Partner Message · · ·
And you can keep the coffee.
This is an advertisement.
☕ Key Insight:
The 2027 family HSA limit is `$9,000`, plus `$1,000` at 55. If Medicare is on the horizon, stop contributing six months before you apply, or the backdated months turn savings into excess.
Coffee Break Move
Before your second cup, pull out your benefits packet. Open enrollment is the moment this gets set for next year.
If you are comfortable: confirm your plan is HSA-eligible, then set payroll contributions to the full limit, catch-up included. Claiming Social Security or Medicare within a year? Mark a date six months earlier to stop.
If you are stretched: even `$50` a paycheck counts. In the `22%` bracket, roughly `$15` of every `$50` is tax you are not paying.
Ernie added one sticky note to the red folder: stop the HSA in the spring before he files. It may be the most valuable note in the house.

Keep Reading