☕ DrinkCoffeeAndProfit
Smart money moves before breakfast
Inspiration Quote for the Day
“It’s not how much money you make, but how much money you keep.”
Robert Kiyosaki
The Morning Ritual
Could You Sell Stock This Year and Owe Nothing? For Many Retirees, Yes.
When did you last sell a stock you have owned for years? For a lot of us, the answer is never. Handing the IRS a slice of a gain that took decades to build feels wrong.
Here is what caught my eye. For millions of retired couples, the federal tax rate on that gain is zero this year. And the window to use it closes on December 31.
In One Sip
► In 2026, long-term capital gains are taxed at 0% when taxable income is at or below $98,900 for married couples. Source: IRS.
► For single filers, the 0% line sits at $49,450. Source: IRS.
► Taxable income is what is left after deductions. The 2026 standard deduction is $32,200 for married couples and $16,100 for singles. Source: IRS.
► Above the line, most gains are taxed at 15%. Source: IRS.
► The buried part: the wash-sale rule only blocks losses. You can sell a winner and buy it right back the same day.
Taxes decide how much of a gain you keep. Our partner below writes about where the next big energy gain could come from.
· · · Partner Message · · ·
In 1976, Chevron tapped an energy source so powerful it could run a city, then killed the project, and Unocal and Texaco did the same.
Now one company has spent sixty years perfecting what Big Oil refused to touch.
Google locked in a 15-year contract, Bill Gates wrote a $100 million check, and on October 20th, the government hands it an edge no other energy source gets.
See the company that didn’t wait >>
This is an advertisement.
Why It Matters for Your Money
Picture a retired couple with $60,000 of taxable income from a pension and part of their Social Security.
They have $38,900 of room before they reach $98,900. Gains that fit in that room are taxed at 0%.
Say they own a fund bought for $20,000 that is now worth $58,900. That is a $38,900 gain.
They sell it and buy the same fund back the same afternoon. The tax bill is zero, and their cost basis is now $58,900.
If they had sold it later at the 15% rate, that same gain would have cost about $5,835. Resetting the basis this year wipes that future bill.
Sound familiar? This is called tax-gain harvesting. Few people do it, because it feels backwards to sell a winner.
Your cost basis is measured in dollars. Our partner below argues the dollar system itself is under strain.
· · · Partner Message · · ·
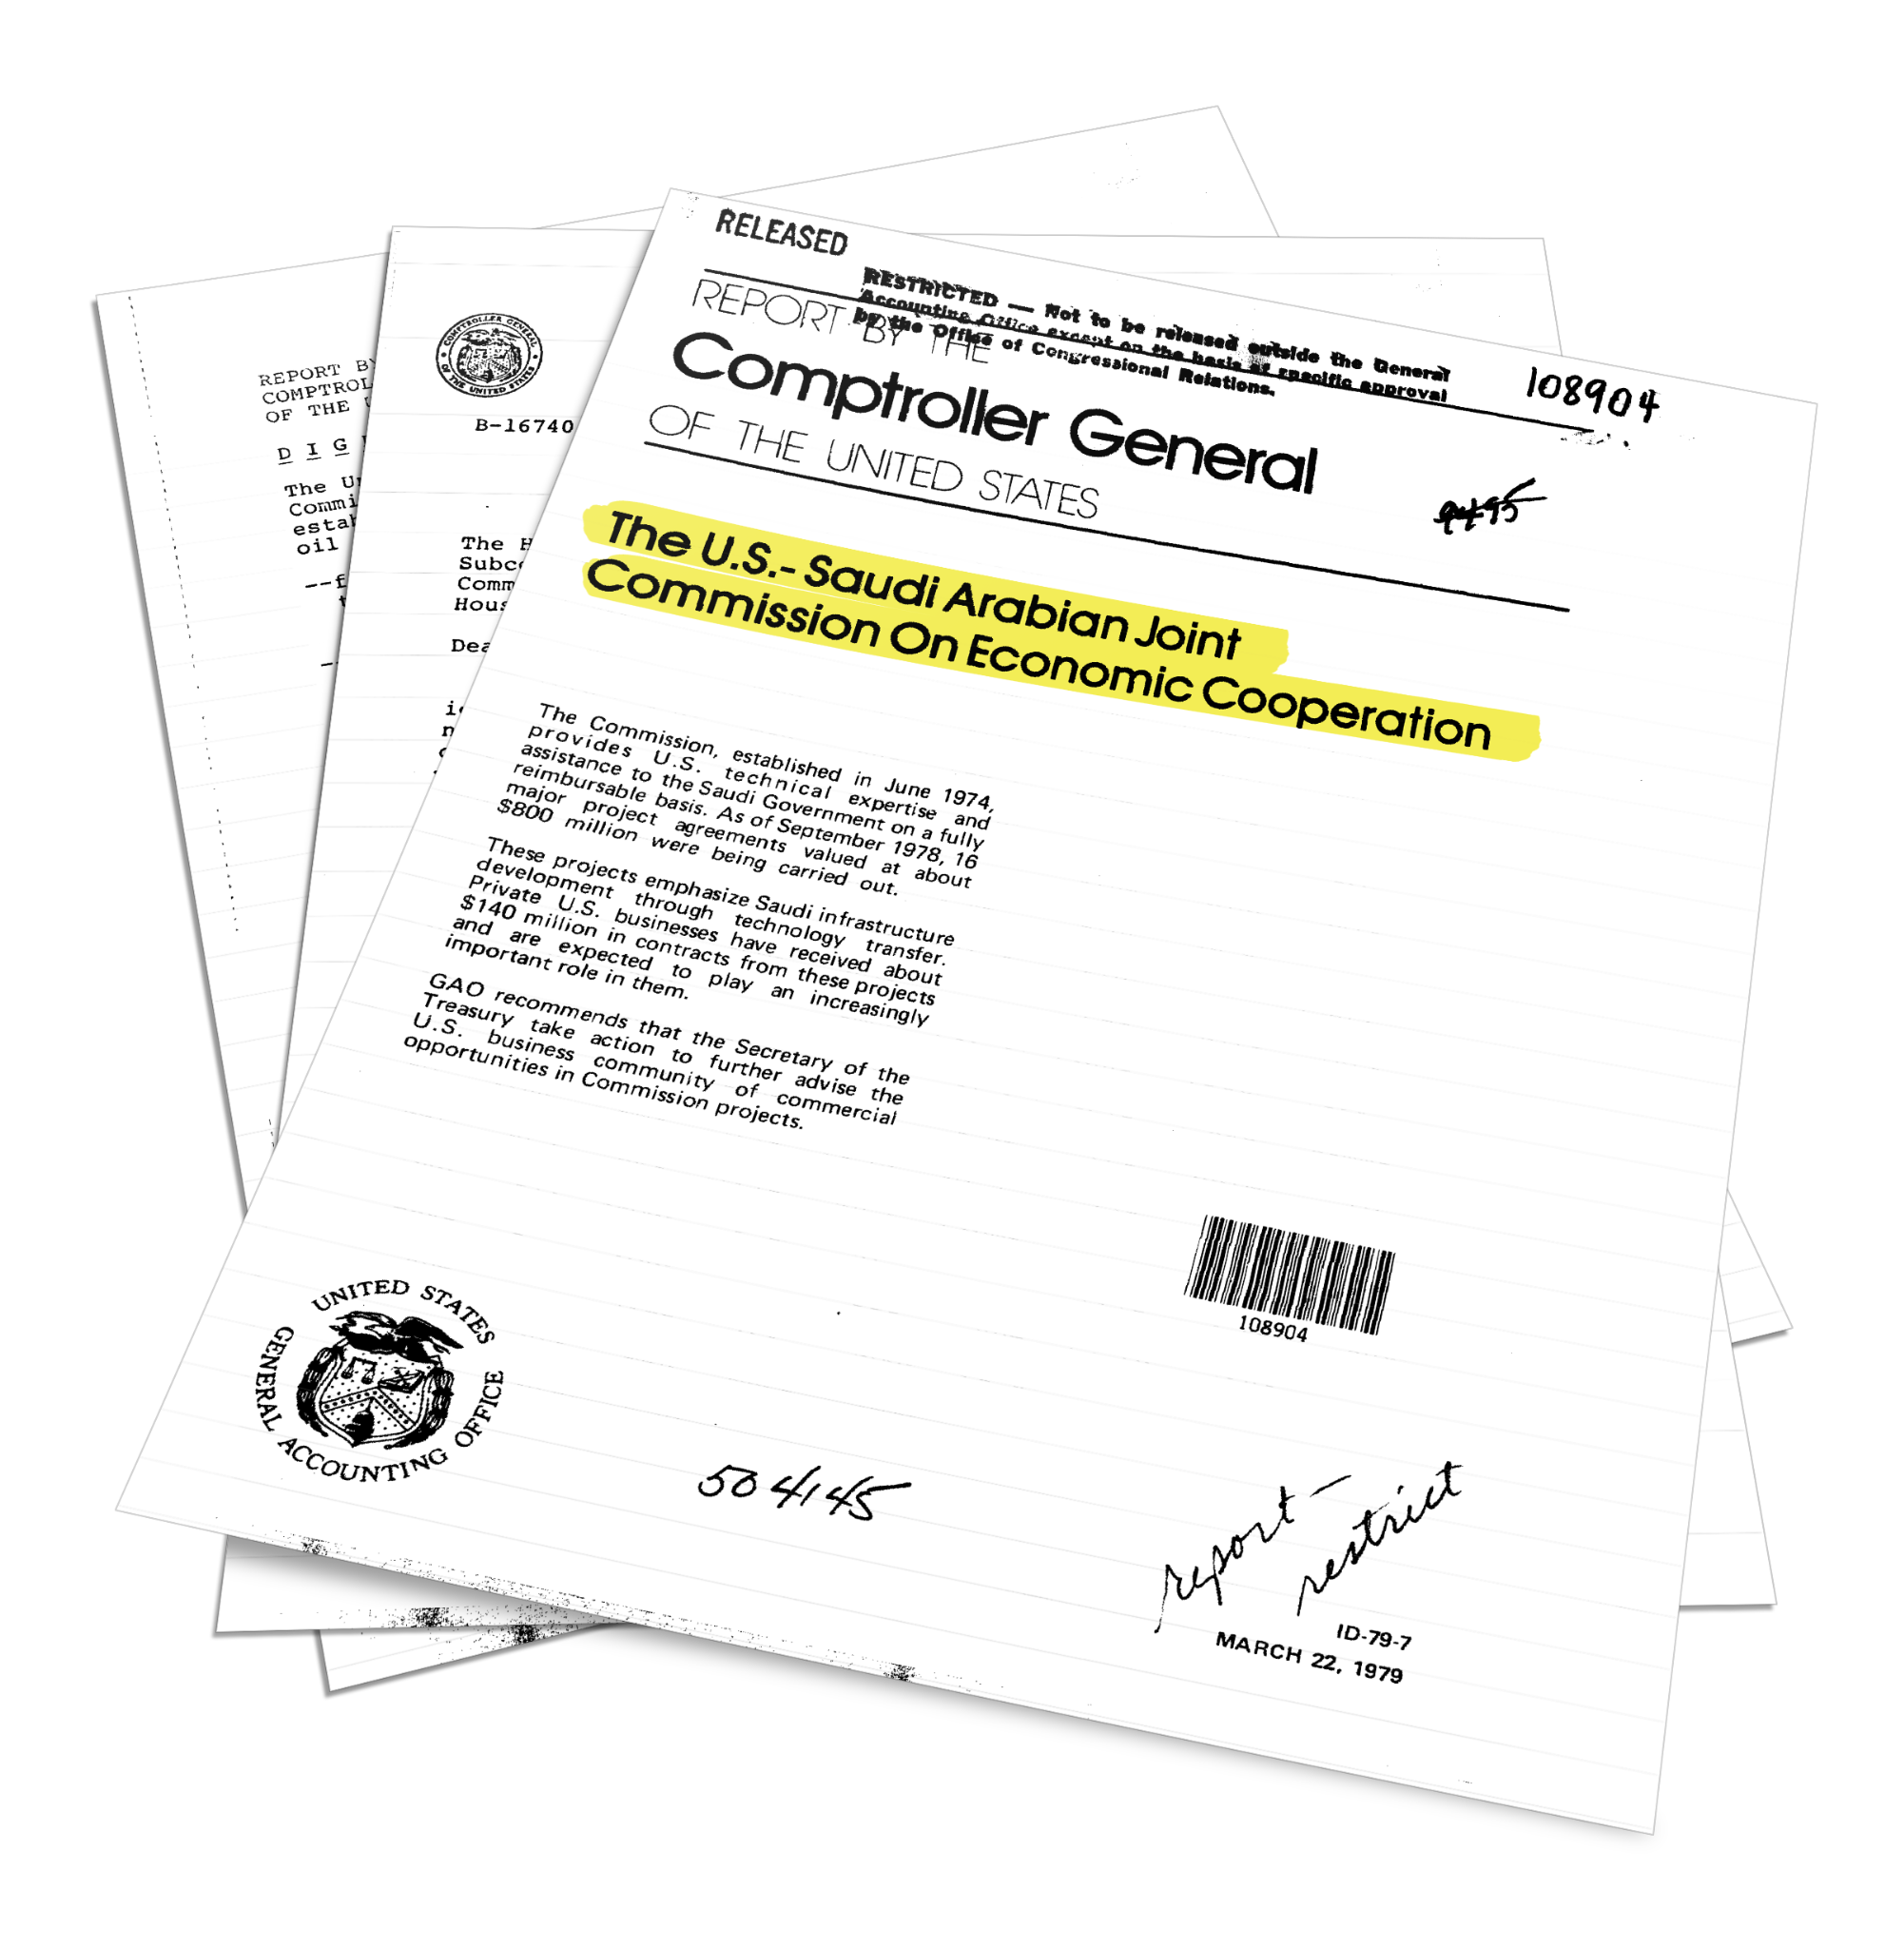
Take a look at this formerly classified document:
Formerly classified document
Most people (professionals included) have never heard of it…
But it’s been quietly protecting the value of your savings, your retirement, and every dollar in your wallet for the last 50 years.
Created under Henry Kissinger in 1974…
It had a name only Washington could love: The U.S.-Saudi Arabia Joint Commission on Economic Cooperation.
For half a century, it helped tie global oil trade to the U.S. dollar…
And protecting the purchasing power of every American who ever saved money, owned a home, or built a retirement account.
On June 9, 2024… It ended quietly.
Now, the war in Iran is shining a huge spotlight on its downfall.
• Stocks crushed 40% to 80% in real terms.
• Real estate cut in half as buyers vanish.
• Inflation grinding at 10% to 15%, month after month, year after year.
Please understand, if you own stocks, bonds, real estate, cash, or a retirement account tied to the U.S. dollar…
You need to read this short presentation now.
It could be the difference between being blindsided by the reset…
And positioning yourself in the tiny group of gold stocks I believe could soar as the dollar system cracks.
Click here now
Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio
This is an advertisement.
The Wealth Angle
Here is where it gets interesting. A capital gain still counts as income for other rules, even when the tax rate on it is zero.
It can push more of your Social Security into taxable income. It can raise your income for marketplace health insurance. And many states tax it no matter what.
Think about that for a second. The federal rate can be zero while the true cost is not.
I think this works best for retirees who have not started Social Security yet, or whose income sits well under the line. Run the numbers with a preparer before you sell.
☕ Key Insight:
Married couples with taxable income up to $98,900 pay 0% on long-term gains in 2026. Selling and rebuying can reset your cost basis tax-free before December 31.
· · · Partner Message · · ·
Something strange is happening to the U.S. dollar.
This is an advertisement.
Coffee Break Move
Before your second cup, pull last year’s tax return and find your taxable income line.
If you are comfortable: subtract it from $98,900, or $49,450 if single. That gap is your room for gains this year. Ask your preparer to check how a sale affects your Social Security and health insurance.
If money is tight: skip the selling and simply note the number. Knowing your room matters most in a year when you need to sell anyway.
Either way, put December 1 on the calendar, so the year-end rush does not make the decision for you.

Keep Reading